
Don’t walk away from the right house for a reason that may scare you.
We’re breaking down some of the most common scares, worries, and anxiety our buyers have come to us with, and why they should be concerned, but not alarmed. Here are 10 “deal breakers” with common fixes and how we handle them.
1 | Well Water and Septic System
Not scary. Just different. Well-kept systems last decades.
Septic systems and well water get a bad rap, but they’re just…different! A well-maintained septic system can last decades if it’s pumped every 3–5 years. As a buyer, you’ll also have a chance to have the septic tested by a septic inspector, and that is a great opportunity to ask them everything you want to know about septic systems. The home inspector will also test the well water and you will receive a report with results. If you want extra peace of mind, add a filter or reverse osmosis system. If there is anything wrong with either, your real estate agent can negotiate with the sellers for a credit or repair. Plus, did you know that having well water means you don’t have to pay a water utility bill? That is one big perk, I’d say!
2 | A Long Inspection Report
Every house has a list. Even brand-new ones.
One of the most overwhelming parts of purchasing a home has to be the home inspection. Don’t be discouraged by the list your home inspector provides you with shortly after, as there is something to find in every home. No home is perfect. Once the inspection is complete, we will review the list of items and may approach the seller to negotiate for a credit, repair, or lowered purchase price. We will be with you every step of the way, as we know this part of the process can be daunting and overwhelming, but home inspectors are paid to be thorough. In the over 300 home purchases we’ve assisted with, only a handful of buyers have walked away from the deal after the home inspection.
3 | It Needs Work
No cash for the kitchen? There’s a loan for that.
Ever heard of a renovation loan? With this loan, your monthly payment will include the mortgage and the cost of renovations or repairs. If that’s not your thing, personal loans and HELOC is also an option. Remember, not everything needs to be renovated or fixed immediately. Live in the house, see what you want to fix first, or see if there are things you can actually live with. Who knows – the avocado bathroom might grow on you! If this is your forever home, take your time renovating rooms so you get it perfect the first time. Homes are investments, and renovations will provide you with great ROI.
Also – location, location, location. If you love the neighborhood and setting, but aren’t crazy about the kitchen, bathrooms, flooring, or something else, those things can be changed. The location cannot ever be changed. Weigh the pros and cons of the location vs property. Plus, you may gain a little sweat equity!
4 | The Paint
Hate the colors? That’s a weekend.
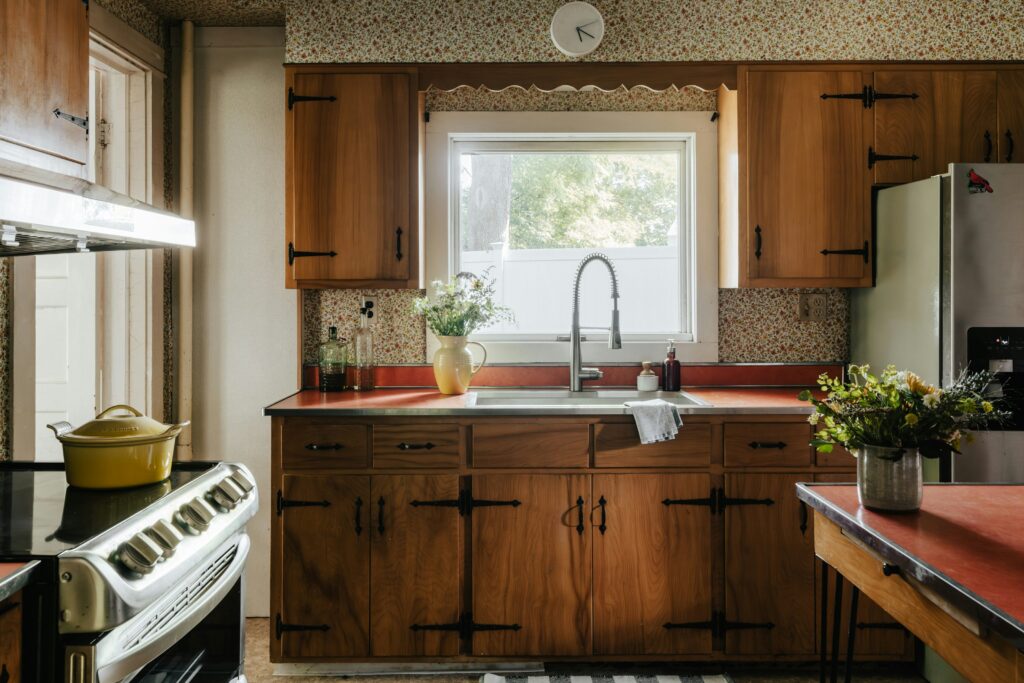
While we always advise our seller clients to paint any dark or outdated rooms to a bright, neutral color, it doesn’t always happen, and now you’re the one looking at drab walls. It’s a good thing paint is one of the easiest and cheapest fixes to make, ranging anywhere from $300 to $1,000 per room. Try to look past wall colors or wallpaper that isn’t your style. Think of it as your first home project!
5 | The Seller’s Decor
Their stuff leaves with them. Picture the room empty.
This is another case where you need to tap into your creative eye. Try to picture the rooms without the furniture, and look at the bones, the light, and the layout. Visualize your furniture in their space, the new rug you will get for the living room, and all the ways you can make this home yours. If you love the house, but hate the owner’s decor and furniture, that’s the best-case scenario, because the owners will be taking their furniture with them!
6 | Radon
Common in CT. Usually fixed in a day.
Radon is very common in Connecticut, and scary to buyers because it is an invisible gas that can cause lung cancer. Around the time of the inspection, an inspector will place a test in the basement, and if it tests at or above the EPA action level of 4 pCi/L, a mitigation system is usually installed in a day. A common misconception is that having a radon mitigation system in place means that the house hasn’t been well taken care of, but that’s not the case at all. A radon mitigation system is a set of pipes that allow the radon gas to blow outside the house with the help of a fan. No more radon!
7 | Mold in the Attic or Basement
Don’t panic. Find the moisture. Fix the cause, fix the problem.
This is also very common and should be cause for concern, but not alarm. In an attic, mold often comes from poor ventilation. In an unfinished basement, it usually comes from humidity or drainage. Fix the source, then remediate. You can also install a vent, fan or dehumidifier and monitor the situation. If your home inspector is thorough (and all of ours are), if they can spot any mold, you can treat it.
8 | Mice
Welcome to New England. A pest pro and some sealing, and you’re done.
With the colder season approaching, it’s time for mice to find a nice cozy spot to live… like a basement or attic. Unfortunately, this is just a part of living in New England. Inspect every inch of your home and find holes they may be able to crawl through and seal them up. This is also why mice traps and pest control businesses exist! Remember, there will be creepy crawlies in every home, whether it’s mice, bats, spiders, bugs, termites, or bees.
9 | Buried Oil Tank
Test it. Remove it. Negotiate it. You have options.
Oil is a very common type of fuel in Connecticut, especially in older homes. When owners convert to gas fuel, they may bury their discarded oil tank in the ground, but many buyers have concerns over oil leaking into the ground and water. A lot of buyers will ask the sellers to remove the oil tank before closing, or negotiate a credit to do so after closing. We have handled this situation on both the seller and buyer side, and highly recommend removal of the oil tank before any further damage can be done – like seepage as the steel body corrodes. A removal can cost anywhere from $1,000 – $4,000, and can be negotiated with the seller.
10 | FHA or VA Loan
20% down isn’t the rule. Sometimes it’s 3.5%. Sometimes it’s zero.
Did you know there are many different types of loans? Based on your income, credit score, debt-to-income ratio, down payment amount, and purchase price will determine what type of loan you’re qualified for. A stigma that FHA loans are undesirable comes from a few criteria: the home must meet property standards and repair requirements, buyers most likely have smaller down payment amounts or lower credit scores, and there is a lifetime insurance added onto the loan. VA loans are similar in that the home must meet standards. While these two loans aren’t as common as a conventional loan or cash offer, they are still widely accepted. Our mortgage broker partners can help in assisting with the loan type that works best for you and your lifestyle.


